
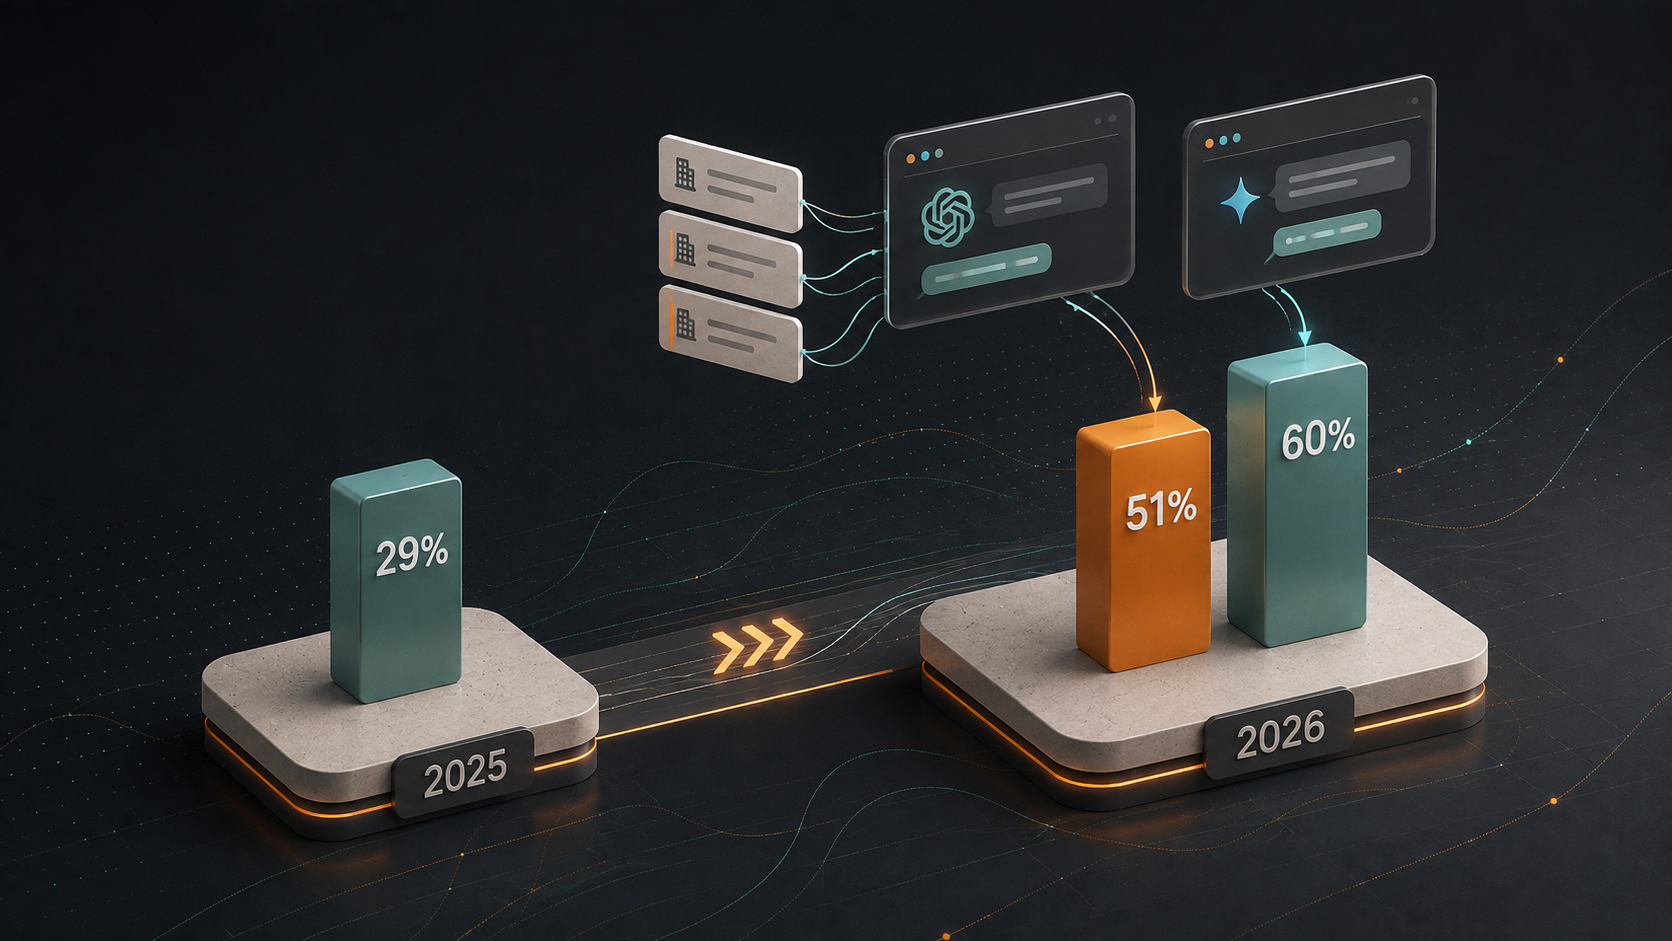
Alt text: AEO and GEO pricing models showing audit, project, and retainer approaches for AI search optimisation services.
A services market has formed in under two years around a single problem: getting brands mentioned inside AI-generated answers rather than ranked in a list of blue links. Reading its pricing as a dataset, rather than as marketing, is a useful exercise. The structure of what these providers charge tells you how mature the discipline is, how measurable its outputs really are, and where it is still guessing.
Key takeaways
- A new provider category exists, selling optimisation for AI answers rather than search rankings.
- Three pricing models dominate: one-off audits, fixed-scope projects and monthly retainers.
- Retainers lead because the core outputs, citations and share of voice, compound slowly and need continuous monitoring.
- Australia is a rare worked example, with a handful of agencies publishing rates openly rather than behind a form.
- The figures are directional, not settled: rate cards remain scarce and “AI share of voice” is not standardised, so numbers signal an industry finding its price rather than a fixed one.
A services market that appeared almost overnight
Two overlapping disciplines sit underneath this market. Answer Engine Optimisation (AEO) aims to make a brand the direct answer an assistant returns to a question. Generative Engine Optimisation (GEO) aims to make a brand retrievable, cited and accurately represented inside a synthesised response. In practice, most 2026 providers use the two terms for the same body of work, because the technical requirements overlap: accessible content, clear structure, defensible evidence and consistent entity information.
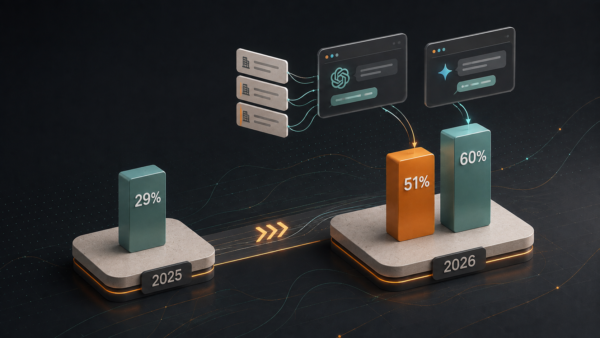
The demand rose because buyer research moved. Google’s October 2025 study with NRG found that around 60% of B2B buyers now use tools such as ChatGPT or Gemini to build and augment vendor lists. G2 recorded a sharper shift in software specifically, reporting in March 2026 that 51% of buyers begin research in an AI chatbot, up from 29% a year earlier. When the first draft of a shortlist is assembled inside an assistant, absence from that answer is a commercial problem, not a vanity one.
That demand produced supply. A distinct provider type has formed around it, essentially a new kind of AI SEO agency that engineers content for citation rather than for ranking. The category is young enough that job titles, deliverables and metrics still vary between vendors, which is exactly why its pricing is worth reading closely.
Alt text: Chart showing the growth of B2B buyers using AI assistants like ChatGPT and Gemini for vendor research and software purchasing decisions from 2025 to 2026
Reading pricing models as a maturity signal
Three commercial structures recur across the market, and each reveals something about how confident the field is in its own outputs.
- One-off audits name the citation gap without committing to fixing it. An economical version simply lists where a brand is absent; a deeper diagnostic classifies why. That distinction matches what pricing research finds across the market: audits work precisely because they solve the problem retainers create, letting buyers see proof before committing to ongoing spend. The prevalence of the audit as a product tells you buyers still want to verify the problem exists before finding a solution.
- Fixed-scope projects package a defined set of deliverables, such as a content build or a schema overhaul, for a set fee. As one pricing breakdown frames it, this model works because it has a clear start, a clear end and a clear deliverable, which suits a confirmed, bounded problem rather than an open commitment.
- Monthly retainers see continuous gap closure and measurement. Market analysis points to the same driver behind their dominance: AI search results change frequently, so maintaining visibility depends on consistent, ongoing work rather than a single fix. They dominate the higher end of the market, and their prevalence is the clearest signal of all about how the work actually behaves.
Monthly retainers fund continuous gap closure and measurement. This points to the same driver behind their dominance: AI search results change frequently, so maintaining visibility depends on consistent, ongoing work rather than a single fix. They dominate the higher end of the market, and their prevalence is the clearest signal of all about how the work actually behaves.
| Pricing model | Typical structure | What it signals | Best suited to
|
|---|---|---|---|
| One-off audit | Fixed fee, single deliverable | Buyers verifying an unproven problem before spending | Diagnosing the gap before committing |
| Fixed-scope project | Set fee for defined deliverables | A bounded, confirmed problem with a known fix | One specific build or correction |
| Monthly retainer | Recurring fee, ongoing scope | Outputs that compound and need continuous measurement | Sustained citation programmes |
Why retainers dominate a compounding discipline
Retainers win because the outputs of this work do not arrive on a project timeline. Citations move over weeks and months as content is retrieved, corroborated and re-retrieved, so a single content push rarely settles a gap. An analysis of 3.5 million citation events found a median citation half-life of just 4.5 weeks, meaning half of what a page earns one month is typically gone the next, with the exact decay rate varying by platform.
Measurement compounds the effect, since generated answers shift as prompts are reworded, models update, or sources change. A synthesis of six 2026 citation studies found only 10.6% of cited URLs held their position across three tracking waves over 28 days, which is why visibility has to be tracked against a stable prompt set over time rather than checked once.
Australia as a worked example
Published rates are scarce in this market, which makes the few transparent ones analytically useful. Australia is a helpful case: a developed, English-language market where a small number of providers list prices openly rather than gating them behind a discovery call. One such breakdown of AEO pricing in Australia is a useful reference point for a single market, because it shows how cost maps to audit depth, retainer scope and reporting cadence.
The pattern in that data is instructive. As of mid-2026, AEO and GEO retainers in the market are described as running from roughly A$3,000 to A$15,000 a month, with anything under about A$1,500 treated as rebranded SEO rather than citation engineering. A one-off diagnostic sits near A$2,500, with retainers starting a little above A$3,000 and scaling with the number of prompts tracked, the volume of assets produced and the reporting rhythm, which tightens from monthly to fortnightly at higher tiers. Price tracks scope and measurement rigour more than it tracks brand. That is what a professionalising market looks like: cost that maps to defined deliverables rather than to positioning.
These figures describe one country at one point in time. They are a directional signal of how the work is being valued, not a global benchmark.
The data problem the market has not solved
For all the pricing structure, the field still lacks the measurement standards that would let anyone compare value across providers.
The core metric, “AI share of voice”, is not standardised, since vendors count mentions, citations and accurate representations differently. Averi’s analysis found only around 11% of domains cited by ChatGPT are also cited by Perplexity, with Passionfruit independently finding 12% overlap across three platforms. A number that averages across engines can therefore describe a position that exists nowhere in particular.
Tracking is also thin. Averi’s March 2026 analysis found only 22% of marketers currently track AI visibility at all, so most of the market is being priced and sold ahead of the measurement infrastructure that would validate it. Rate cards compound the gap, since the sample of published prices is self-selected, reflecting the agencies confident enough to publish rather than the market as a whole.
What the pricing structure tells us about where the field is heading
Two trajectories show up in the pricing at once. The field is professionalising where providers price diagnostically, classify root causes before recommending a fix, and publish tiered rates that map to defined deliverables. This pattern matches what research on professional services pricing models identifies as diagnostic pricing, an established practice where a paid initial assessment shapes the scope and fee of the work that follows. Those are the habits of a discipline building a method rather than selling a promise.
It remains guesswork where the outcome-per-dollar has no benchmark and share-of-voice definitions differ between vendors. Semrush’s 2026 AI Visibility Index, built from 126 million AI search prompts, found that 45% of marketing leaders cannot accurately measure brand visibility in AI-generated answers, and only 9% have tools to track all the relevant metrics. For data teams and buyers watching the market mature, the useful signals are specific: whether metrics converge on shared definitions, whether outcome benchmarks get published rather than just prices, and whether an audit classifies why a gap exists rather than only that it does.
The pricing of AEO and GEO is, in the end, a market pricing its own uncertainty. Read as data, it shows a discipline that has already agreed on how to charge for the work, and has not yet agreed on how to measure it. Agencies now converge on rate ranges even as measurement standards stay inconsistent and platforms keep changing underneath them. The gap between those two is where the next phase of this industry will be decided.
AEO and GEO FAQs
What is the difference between AEO and GEO?
AEO optimises to be the direct answer an assistant returns, while GEO optimises to be retrieved, cited and accurately represented inside a generated response. In practice most providers now use the terms for the same discipline, because the underlying requirements overlap heavily.
Why do AEO and GEO agencies favour retainers over project fees?
Because the outputs compound slowly and the measurement is continuous. Citations move over weeks and months, and answers shift when prompts, models or sources change, so visibility has to be tracked against a stable prompt set over time rather than delivered once.
Are published AEO rates reliable benchmarks?
They are directional, not definitive. Rate cards are scarce, the sample that gets published is self-selected, and metrics are not standardised across vendors. Treat public prices as a reference point for one market rather than a fixed industry rate.
How should a buyer read an “AI share of voice” figure?
Carefully, and per engine. A single averaged number can hide large differences between platforms, since a brand cited often on one engine may be absent on another. Ask which engines were measured, over what prompt set, and how mentions and citations were counted.
Author Bio
Ronan Leonard is a Certified Innovation Officer and founder of Intelligent Resourcing. He designs go-to-market workflows that connect strategy with execution, with expertise in Clay automation, lead generation automation and AI-first revenue operations. His work helps B2B organisations improve how their expertise is discovered, understood and cited across conventional and AI-led search, while building growth systems designed to increase pipeline and reduce customer acquisition costs.